Category Archives: Trades

Doubling Down on Altius Minerals (TSX:ALS)

I decided to double my investment in Altius Minerals (TSX: ALS, Pink Sheets: ATUSF) after the company’s stock price plummeted by more than 40%. I originally analysed the company here. The reason for the collapse was that Altius was notified by Newfoundland and Labrador Refining Corporation (NLRC) that it was seeking creditor protection after SNC-Lavalin, an engineering firm which provided services for NLRC, served NRLC with a notice of proceedings that it was seeking to have NLRC declared bankrupt.

Altius Minerals is the largest holding in my portfolio because I was very optimistic that its investment in NLRC could be worth several billion dollars in a few years. Indeed if the refinery was up and running today it would be enjoying gross margins well above the $26 I used to value the company last December. And no other refinery project in North America has succeeded in obtaining all the environmental permits as NLRC has.

My take on the dispute between SNC-Lavalin and NLRC is that SNC-Lavalin has not been paid for its services and is trying to leverage that into an equity stake. I could be wrong, but I cannot see how SNC-Lavalin will gain by seeing NLRC bankrupt. Even if SNC-Lavalin were awarded all of the assets of NLRC, which would not be worth the $20 million they are owed or millions more they stand to make in future services, it would be difficult for it to go ahead and complete the refinery without the support of Altius’ management who are Newfoundlanders with immense support from the provincial government and the local community.

I would be surprised if SNC-Lavalin and NLRC do not come to an out of court settlement within the next few months. Altius and the other investors of NLRC may need to concede equity to SNC-Lavalin to resolve the issue, but it would be best for all parties involved to not see NLRC bankrupt.

But even if we assume that the refinery project is dead then Altius’ loss should be limited to the $52 million invested in NLRC. Altius still has around $8 of net asset value per share and at Friday’s closing price of around $7, this would constitute an attractive value investment. Management has a track record of steadily growing net asset value over the long run and with Altius’ large holdings of resource rich land in Newfoundland, I have no doubt that shareholder value will be created over time. I bought a lot more stock on Friday at an average price of $7.10.

Shorting Washington Mutual (NYSE:WM)

As mentioned in a previous post, I am short Washington Mutual (NYSE:WM) at an average price of $11.94. I think the country’s largest savings and loan institution owns a portfolio of very risky mortgages and consumer loans that could eventually render it insolvent.

Most economists have started to accept that average home prices will decline by 20% from peak to trough. I think prices could fall 25-30%. Even if we assume that 20% will be the correct number then, according to Calculated Risk, almost 14 million single family homes will have mortgages worth more than the value of the homes.

If 4 million of these homeowners actually walk away from their homes and we get another 2 million defaults due to loss of jobs, business income, etc. then the US could be facing 6 million foreclosures in the coming years. Assuming that the average mortgage balance on these homes is around $300,000 and half of the value of the mortgages are eventually recovered then the total mortgage losses will amount to almost $1 trillion or 10% of the total outstanding mortgage balance.

If such a scenario plays out, then WaMu is in big trouble. According to its 2007 annual report, the bank held $244 billion of loans, half of which were originated from California and another 8% from Florida. Among the loans were $9 billion of credit card loans, $18.5 billion of subprime mortgages, and $61 billion of HELOC. In addition, $110 billion of mortgages to prime borrowers were held of which half were option ARMs. Also, half of the $110 billion prime mortgages had loan-to-value ratios exceeding 70%. And the most disturbing part is that WaMu had set aside only $2.6 billion for total loan losses.

I think there is a good chance that WaMu will have to write-off an additional $25 billion of these loans or approximately 10% of the portfolio. There could be another $3 billion of write-offs for some of WaMu’s other assets. For instance, it held $1.5 billion of asset backed securities (ABS) with underlying credit card loans that the rating agencies have rated as junk, meaning that if credit card charge-offs continue to rise WaMu’s ABS could be worth very little.

In total I think WaMu will have to write-off at least another $28 billion over the next few years. It recently raised $7 billion in a preferred share offering, but if the bank’s $7.3 billion of goodwill is excluded, then the total tangible equity amounts to $24 billion, which would be insufficient to deal with my estimate of future losses.

WaMu’s only chances of survival are raising additional equity or selling itself to another bank. But another equity offering will only be completed well below the current price and would again massively dilute shareholders. A takeover of WaMu by another bank is quite possible, however the bank recently rejected J.P. Morgan’s offer of $8 per share and instead agreed to an equity offering that almost doubled the share count. A future takeover will only be completed well below $8.

If substantially more capital is not attracted from investors, WaMu’s book value will head towards zero. Over time that will become more apparent leading to a run on the bank, which would be the final nail in the coffin as deposits are a major funding source for WaMu. The end result could be the Fed and the government stepping in and nationalizing the bank, but not before current shareholders are wiped out.

At the current price WaMu looks to me like an easy short sell.

Prepared For a Bear Market

Until late January I was aggressively long gold and commodity stocks believing that the Fed would be able to confront any economic downturn by printing more money which would immediately cause lots of inflation and rising asset prices.

The fact of the matter is that the Fed has printed very few dollars in recent years and the primary growth in money supply has been fueled by credit growth. But if we are facing trillions of dollars of credit losses then we will not see any credit growth, but rather credit contraction as the bad debt is written off and banks try to preserve equity.

It’s true the Fed can combat this credit contraction by creating enough money, but until now very little money has been printed. Any amounts of cash or treasuries that the Fed has lent out in excess of what it owns on its balance sheet, has been borrowed from the markets. That is, the Fed’s balance sheet has not grown although its composition has changed. And the federal government’s $150 billion stimulus amounts to a drop in the bucket compared to the credit losses.

Simply put the Fed and the government are one step behind the ball and I fear it could take a couple of years before they are able to create enough inflation to stem the losses. That means that the high inflationary environment that is very bullish for gold and other commodities may not appear for awhile. Instead a deflationary panic could ensue causing resource stocks to plummet.

So I have sold most of my stocks keeping only the few I like the most. I have not sold any of my shares in Altius Minerals (TSX: ALS). I am also keeping a few of my very favorite junior exploration stocks. I have purchased the Elements Rogers International Commodity Agriculture ETN (AMEX: RJA) because I think agriculture can still do well in this kind of environment. I am also in the process of buying physical gold.

I have sold everything else including PICO Holdings (Nasdaq: PICO), which I wrote extensively about recently. I like PICO’s water business in the long-run, but in the short-run it is very dependent on homebuilding and municipal spending. PICO has a book value of $28 per share so there isn’t much downside risk, but during market panics you can never tell, which is why I am selling.

I am aggressively shorting financials through the ProShares UltraShort Financial ETF (AMEX: SKF) and I am shorting Washington Mutual (NYSE: WM), which I think is on the path to bankruptcy unless it gets taken over. Also, I have written put options on MBIA (NYSE:MBI) with a strike price of $10. The total value of my shorts is equal to about 40% of the value of my longs.

Eventually, I believe the Fed will create enough money to cause inflation to sky-rocket and I will be significantly overweight resource stocks again. However, the key to being a successful speculator is knowing when to pull in your reins and not make risky bets. I think that time is upon us.

Buying PICO Holdings (Nasdaq: PICO)

In my previous post, I explained why the US Southwest is on the brink of facing a water crisis and why it is important that the large allocation of water for agriculture be shifted to residential and industrial use. There is one company which specializes in acquiring water rights from farmers and selling them to municipalities at a profit. That company is PICO Holdings (NASDAQ: PICO), which I own and view as an attractive value investment.

PICO operates four different businesses through subsidiaries:
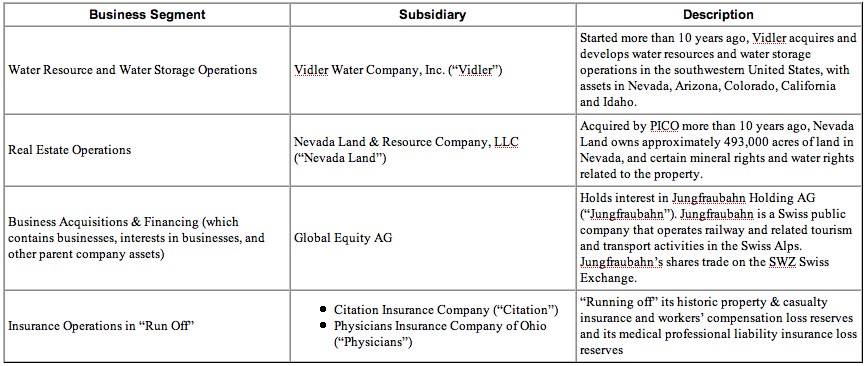
PICO

Most of PICO’s assets do not produce regular income, so the best way to value the company is on a book value basis. Using this measure, management has done a good job growing book value per share. In less than 5 years book value per share has increased by 56%.

2007/9/30 = $27.90
2006/12/31 = $25.52
2005/12/31 = $22.67
2004/12/31 = $19.40
2003/12/31 = $18.52
2002/12/31 = $17.86

But I believe PICO’s assets are worth much more than what’s stated on its balance sheet. To see how, let’s examine each of PICO’s business segments.

Water Resource and Water Storage Operations

For the last 10 years, PICO’s water resource development subsidiary, Vidler Water Company, has been accumulating and developing water rights in carefully chosen locations in Nevada and Arizona, in anticipation of the strong population growth and shortage of water that is occurring now. Vidler seeks to allocate its water supplies to municipal and industrial use in a way that maximizes profits. Vidler frequently operates in areas where rapid population growth occurs in municipalities that lack the financial or technical resources to develop new supplies of water.

The inefficient allocation of available water between agricultural users and municipal or industrial users, or the lack of available known water supply in a particular location, provide opportunities for Vidler:

  • the majority of water rights are currently owned or controlled by agricultural users, and in many locations there are insufficient water rights owned or controlled by municipal and industrial users to meet present and future demand;
  • certain areas of the Southwest experiencing rapid growth have insufficient known supplies of water to support future growth. Vidler identifies and develops new water supplies for communities with no other known water resources to support future growth. In certain cases, to supply water from the water resources identified by Vidler, it may require regulatory approval to import the water from its source to where development is occurring, or substantial infrastructure to convey the water. Vidler is able to assess the likelihood of being able to get the necessary approval to import water, and to build the infrastructure in a timely and economic manner. In cases where it assesses that water importation is possible, Vidler has demonstrated an ability to obtain all of the required approval and entitlements, and to manage the building of the infrastructure necessary to import and convey the identified water from its source to development; and
  • currently there are not effective procedures in place for the transfer of water from private parties with excess supply in one state to end-users in other states. However, regulations and procedures are steadily being developed to facilitate the interstate transfer of water. Infrastructure to store water will be required to accommodate and allow interstate transfer, and transfers from wet years to dry years. Currently there is limited storage capacity in place.

Vidler is engaged in the following activities:

  • supplying water to end-users in the Southwest, namely water utilities, municipalities, developers, or industrial users. The source of water could be from identifying and developing a new water supply, or a change in the use of water from agricultural to municipal and industrial; and
  • development of storage and distribution infrastructure to generate cash flow from the purchase and storage of water for resale, and charging customers fees for “recharge,” or placing water into storage.

Vidler’s priority is to either monetize or develop recurring cash flow from its most important assets by:

  • securing supply contracts utilizing its water rights in Nevada; and
  • storing additional water at the Vidler Arizona Recharge Facility, and providing water supplies from net recharge credits (a recharge credit is an acre-foot of water) already in storage.

Vidler has also entered into “teaming” arrangements with parties who have water assets but lack the capital or expertise to commercially develop these assets. The company only extends capital in those areas where initial investigations indicate that obtaining a sufficient quantity of water provides an adequate return on the capital employed in the project. These capital expenditures largely consist of drilling and engineering costs for water production, costs of monitoring wells, and legal and consulting costs for hearings with the State Engineer, and National Environmental Protection Act, or “NEPA”, compliance costs. The first such arrangement is a water delivery teaming agreement with Lincoln County (“Lincoln/Vidler”), which is developing water resources in Lincoln County, Nevada. The following details Vidler’s water rights and water storage assets:

1. Fish Springs Ranch

Vidler owns a 51% interest in the Fish Springs Ranch which contains 13,000 acre-feet of permitted water rights. The company is near completion of constructing a pipeline that could convey 8000 acre-feet of water from the Fish Springs Ranch to a central storage tank in northern Reno, Nevada. Reno is constrained for land that could be developed for residential use because of a lack of water supplies. As a result, the market price of water delivered to Reno has strongly appreciated recently. Once the pipeline is completed, Vidler will seek to sell the water to developers in the northern valleys. The company has already agreed to sell approximately 117.5 acre-feet of water for $45,000 per acre-foot.

The total cost of the pipeline is approximately $90 million, $75 million of which Vidler has already capitalized. In accordance with the Fish Springs partnership agreement, the other partner’s share of the cost is 49% which Vidler will pay, but will be recouped from the net revenues generated from the sale of water from Fish Springs. Therefore, if Vidler is able to sell the remaining water rights for $45,000 (which the company believes is likely) then Vidler’s share of total revenues of $360 million will be approximately $205 million. This would amount to a net increase in book value of approximately $80 million.

2. Lincoln County

The Lincoln County Water District and Vidler (“Lincoln/Vidler”) have entered into a water delivery teaming agreement to locate and develop water resources in Lincoln County, Nevada. Under the agreement, proceeds from sales of water will be shared equally after Vidler is reimbursed for the expenses incurred in developing water resources in Lincoln County. Lincoln/Vidler has filed applications for more than 100,000 acre-feet of water rights with the intention of supplying water for residential, commercial, and industrial use, as contemplated by the County’s approved master plan. This is the only known new source of water for Lincoln County. Vidler anticipates that up to 40,000 acre-feet of water rights will ultimately be permitted from these applications, and put to use for projects in Lincoln County.

Under the Lincoln County Land Act, more than 13,300 acres of federal land in southern Lincoln County near the fast growing City of Mesquite was offered for sale in February 2005. According to press reports, the eight parcels offered sold to various developers for approximately $47.5 million. The land was sold without environmental approvals, water, and city services, which will be required before development can proceed. Additional water supply will be required in Lincoln County if this land is to be developed.

In 1998, Lincoln/Vidler filed for 14,000 acre-feet of water rights for industrial use from the Tule Desert Groundwater Basin. In November 2002, the Nevada State Engineer granted an application for 2,100 acre-feet of water rights, and ruled that another 7,244 acre-feet could be granted, but would be held in abeyance while Lincoln/Vidler pursues additional studies.

In 2005 Lincoln/Vidler entered into an agreement with a developer. The developer has up to 10 years to purchase up to 7,240 acre-feet of water, as and when supplies are permitted from the applications. It is expected that the hearings to permit these applications will commence in 2007. During 2006, Vidler successfully drilled a series of production and monitoring wells to provide evidence to support the applications. The initial price of $7,500 per acre-foot will increase at 10% each year. In addition, the developer pays a commitment fee equal to 10% of the outstanding balance of unpurchased water each year, beginning August 9, 2006, which will be applied to the purchase of water. If the 40,000 water rights that are expected to be permitted in Lincoln County are valued at a conservative $5000 per-acre feet and we assume that it cost Vidler $500 per-acre feet to develop them, then Vidler’s share of the value of the water rights would amount to an increase in book value of $80 million.

3. Vidler Arizona Recharge Facility

During 2000, Vidler completed the second stage of construction at its facility to “bank,” or store, water underground in the Harquahala Valley, and received the necessary permits to operate a full-scale water “recharge” facility. “Recharge” is the process of placing water into storage underground. Vidler has the permitted right to recharge 100,000 acre-feet of water per year at the Vidler Arizona Recharge Facility, and anticipates being able to store in excess of 1 million acre-feet of water in the aquifer underlying much of the valley. When needed, the water will be “recovered,” or removed from storage, by ground water wells.

The Vidler Arizona Recharge Facility is the first privately owned water storage facility for the Colorado River system, which is a primary source of water for the Lower Division States of Arizona, California, and Nevada. The water storage facility is strategically located adjacent to the Central Arizona Project (“CAP”) aqueduct, a conveyance canal running from Lake Havasu to Phoenix and Tucson. The water to be recharged will come from surplus flows of CAP water. The proximity to the CAP is a competitive advantage, because it minimizes the cost of water conveyance.

Vidler is able to provide storage for users located both within Arizona and out-of-state. Potential users include industrial companies, developers, and local governmental political subdivisions in Arizona, and out-of-state users such as municipalities and water agencies in Nevada and California. The Arizona Water Banking Authority (“AWBA”) has the responsibility for intrastate and interstate storage of water for governmental entities.

Vidler has the only permitted, complete private water storage facility in Arizona. Given that Arizona is the only southwestern state with surplus flows of Colorado River water available for storage, we believe that Vidler’s is the only private water storage facility where it is practical to “bank,” or store, water for users in other states, which is known as “interstate banking.” Having a permitted water storage facility also allows Vidler to acquire, and store, surplus water for re-sale in future years.

Vidler has not yet stored water for customers at the recharge facility, and has not as yet generated any revenue from the facility. Vidler has been recharging water for its own account since 1998, when the pilot plant was constructed. At the end of 2006, Vidler had “net recharge credits” representing approximately 115,000 acre-feet of water in storage at the facility, and had purchased or ordered a further 30,000 acre-feet for recharge in 2007. Vidler purchased the water from the CAP, and intends to resell this recharged water at an appropriate time.

Vidler anticipates being able to recharge 35,000 acre-feet of water per year at the facility, and to store in excess of 1 million acre-feet of water in the aquifer. Vidler’s estimate of the aquifer’s storage volume is primarily based on a hydrological report prepared by an independent engineering firm for the Central Arizona Water Conservation District in 1990, which concluded that there is storage capacity of 3.7 million acre-feet.

Recharge and recovery capacity is critical, because it indicates how quickly water can be put into storage or recovered from storage. In wet years, it is important to have a high recharge capacity, so that as much available water as possible may be stored. In dry years, the crucial factor is the ability to recover water as quickly as possible. There is a long history of farmers recovering significant quantities of water from the Harquahala Valley ground water aquifer for irrigation purposes.

Vidler is in discussions with a number of developers and other entities which could lead to the sale of net recharge credits. The company believes that the storage site, the net recharge credits, and Vidler’s remaining water rights and land in the Harquahala Valley could be an attractive combination to developers looking to secure water supply to support new development in the Harquahala Valley, which is approximately 75 miles northwest of metropolitan Phoenix, Arizona.

The Vidler Arizona Recharge Facility is located in La Paz County, close to the county line with fast-growing Maricopa County. According to U.S. Census Bureau data, the population of Maricopa County increased 18.3% from 2000 to 2005, with the addition of more than 110,000 people per year. Vidler anticipates that as the boundaries of the greater Phoenix metropolitan area push out, this is likely to lead to demand for water to support growth within the Harquahala Valley itself. Vidler’s 115,000 acre-feet of net recharge credits should easily generate proceeds of $300 above its costs on a per acre-foot basis. Thus, the Vidler Arizona Recharge Facility could be worth $30 million more than its balance sheet value.

Real Estate Operations

In April 1997, PICO paid $48.6 million to acquire Nevada Land, which at the time owned approximately 1,352,723 acres of deeded land in northern Nevada, and the water, mineral, and geothermal rights related to the property. Much of Nevada Land’s property is checker-boarded in square mile sections with publicly owned land. The lands generally parallel the Interstate 80 corridor and the Humboldt River, from Fernley, in western Nevada, to Elko County, in northeast Nevada.

Nevada Land is one of the largest private landowners in the state of Nevada. According to U.S. Census Bureau data, Nevada has experienced the most rapid population growth of any state in the United States for 19 of the past 20 years, being narrowly edged out by Arizona in 2006. The population of Nevada increased 66% in the 10 years ended April 1, 2000, and increased another 25%, to approximately 2.5 million people, from 2000 to 2006. Most of the growth is centered in southern Nevada, which includes the city of Las Vegas and surrounding municipalities. Land available for private development in Nevada is relatively scarce, as governmental agencies own approximately 87% of the land in Nevada.

Before the acquisition of Nevada Land, the property had been under the ownership of a succession of railway companies, to whom it was a non-core asset. Accordingly, PICO believes that the commercial potential of the property had not been maximized. During the period from April 23, 1997 to September 30, 2007, Nevada Land received consideration of approximately $70.1 million from the sale and exchange of land, and the sale of water rights. This is comprised of $69 million from the sale and exchange of land, and $1.1 million from the sale of water rights related to land that was sold.

Over this period, approximately 814,000 acres of land was divested at an average price of $85 per acre, which compares to an average cost basis of $35 in the acres disposed of. The average gross margin percentage on the disposal of land and water rights over this period is 59.6%. The average cost for the total land, water, and mineral assets acquired with Nevada Land was $35 per acre. Currently, Nevada Land owns approximately 560,000 acres of land. In light of the recent downturn in Nevada property prices, it is reasonable to assume that Nevada Lands real estate would be worth at least $35 per acre above its cost basis. And if sold, PICO’s book value would increase by $20 million.

At December 31, 2006, Nevada Land owned approximately 541,000 acres of former railroad land. In addition to the former railroad property, Nevada Land acquired:

  • 17,558 acres of land in a land exchange with a private landowner. This land is contiguous with Native American tribal lands and is culturally sensitive; and
  • Spring Valley Ranches, which originally consisted of 8,717 acres of deeded land, located approximately 40 miles east of Ely in White Pine County, Nevada. During 2006, we sold approximately 7,675 acres of land and related water assets at Spring Valley.

In recent years, Nevada Land has filed additional applications for approximately 50,600 acre-feet of water rights on the Company’s former railroad lands. Of these applications, approximately 12,400 acre-feet of water rights have been certificated and permitted, and applications are pending for approximately 38,200 acre-feet of water use for agricultural, municipal, and industrial use. Potentially, some of these water rights could be utilized to support the growth of municipalities in northern Nevada.

Insurance Operations in Run-off

This segment consists of Physicians Insurance Company of Ohio and Citation Insurance Company. Both Physicians and Citation are in “run off.” This means that the companies are handling and resolving claims on expired policies, but not writing new business.

Typically, most of the revenues of an insurance company in “run off” come from investment income (i.e., interest from fixed-income securities and dividends from stocks) earned on funds held as part of their insurance business. In addition, from time to time, gains or losses are realized from the sale of investments.

In broad terms, Physicians and Citation hold cash and fixed-income securities corresponding to their loss reserves and state capital & deposit requirements, and the excess is invested in small-capitalization value stocks in the U.S. and selected foreign markets.

Equity Investments

PICO holds $263.5 million worth of marketable equity securities. The most significant holding is Jungfraubahn Holding AG, which has a market value and carrying value of $68.9 million (before taxes). PICO is the largest shareholder by owning 1.3 million shares of Jungfraubahn, which represents approximately 22.5% of that company. At June 30, 2007, Jungfraubahn had shareholders’ equity of CHF 341.6 million or approximately CHF 58.55 (US$53.28) in book value per share. At December 31, 2007, Jungfraubahn’s stock price was CHF 58.00 (US$52.78).

PICO’s $200 million-plus is invested in other publicly listed companies that are also trading at around book value. This value approach to investing should insulate the company’s portfolio from severe declines and in the long-term should lead to steady capital appreciation.

In sum, PICO’s book value could increase by around $210 million over the next few years as the company unlocks value from its real estate and water assets. This is equal to a share price of $39, which makes the company’s shares attractive at its current market price of $33. And if the US Southwest undergoes a water crisis, which I’m afraid is quite likely, then PICO’s stock price should soar. Thus, PICO makes for both a good value investment and a bet on water.
Investing in Water Rights

I believe I have come across an attractive investment opportunity: owning water rights in the US Southwest. Rather than actually buying water rights, it is far easier to buy shares of a publicly traded company that is involved in this space. There is only one which I am aware of and I will discuss it in my next post. But in this post, I will explain why water rights in the Southwest is likely to become much more valuable.

The great basin states of Colorado, Utah, Wyoming, New Mexico, Arizona, Nevada and California mostly depend on water from the Colorado River. The river is replenished by snowmelt from the Rocky Mountains. However, an ongoing drought has reduced the flow of the Colorado to its lowest levels since measurements began 85 years ago.

The obvious culprit is rising temperatures due to either climactic variation or global warming. Indeed, the Colorado River basin is already two degrees warmer than it was in 1976. Rising temperatures can cause snowmelt runoff to decrease, reservoirs to lose far more water to evaporation, and water demand to increase because crops are thirstier.

Meanwhile, the population of the seven states that depend on the river grew by 10% between 2000 and 2006, compared with 5.6% in the rest of America. And much of the growth is in the driest parts of those states. As a result, the supply of water is struggling to keep up with demand and the price of water rights has risen. Municipalities are scrambling to secure water supplies, but there is no new readily available source and if the drought persists, the value of water could soar.

So the big question for anyone thinking of investing in water rights is whether the drought will continue or is it more likely that the Southwest will get more precipitation. This coming spring, the United Nations’ Intergovernmental Panel on Climate Change will issue a report identifying areas of the world most at risk of droughts and floods as the earth warms. The report will identify the Colorado River basin as a problem zone.

Almost without exception, recent climate models envision a reduction in water supply that range from the modest to the catastrophic by the second half of this century. One study in particular, by Martin Hoerling and Jon Eischeid, suggests the region is already “past peak water,” a milestone that means the river’s water supply will now forever trend downward.

Climatologists seem to agree that global warming means the earth will, on average, get wetter. According to Richard Seager, a scientist at Columbia University’s Lamont Doherty Earth Observatory who published a study on the Southwest last spring, more rain and snow will fall in those regions closer to the poles and more precipitation is likely to fall during sporadic, intense storms rather than from smaller, more frequent storms. But many subtropical regions closer to the equator will dry out. The models analyzed by Seager, which focus on regional climate rather than Colorado River flows, show that the Southwest will ultimately be subject to significant atmospheric and weather alterations, which probably has already begun.

I tend to be skeptical of climate models. After all, if we can’t even model the real estate market how are we going to model the weather, which is far more chaotic. However, shifts in weather trends once in place take a long time to reverse. It’s far more likely that the trend towards warmer temperatures in the Southwest over the past 30 years will continue for at least another few years. And the value of water in the region should continue to rise.

Las Vegas is almost certainly more vulnerable to water shortages than any other city in the country. Partly that’s a result of the city’s explosive growth. But the state of Nevada has the historical misfortune of receiving a smaller share of Colorado River water (300,000 acre-feet annually) than the other six states with which it signed a water-sharing compact in the 1920s.

That modest share, stored in Lake Mead, now means everything to Las Vegas. Lake Mead, the enormous reservoir in Arizona and Nevada that is fed by the Colorado River, is half-empty with less than 14 million acre-feet of water, and statistical models indicate that it will never be full again. Since 2001 the flow of water into Lake Mead has been below average for all but one year. If the drought does not break in the next few years, the Las Vegas metropolis will be the first to suffer. Its 1.8m inhabitants depend on the lake for nine-tenths of their water supply.

Fearing that the surface of Lake Mead will soon drop below the level of one of its two pumps, Las Vegas is quickly building another. It has bought ranchland in eastern Nevada and plans to build a pipeline to bring its water hundreds of miles south. Next year it will raise the sum it pays city residents to tear up their lawns and replace them with cacti and other abstemious flora.

Conservation has already reduced water use in Las Vegas from a peak in 2002. Impressively, every drop of water that enters the city’s sewers is cleaned and pumped back into Lake Mead. But conservation alone cannot stave off a crisis on the Colorado River. Its flow might be permanently reduced. The price of water is likely to go up.

Not surprisingly, the prices paid for groundwater rights have skyrocketed in recent years. In Las Vegas developers have moved west 60 miles to Pahrump and 80 miles northeast to Mesquite. There, developers pay upwards of $25,000 an acre-foot for groundwater rights when they can find any. To the north in Reno (about 425 miles north of Las Vegas), developers have paid $50,000 or more for an acre-foot. Thirty years ago, those water rights could be had for $50 an acre-foot (one acre foot is enough to supply one or two average homes). And, just two years ago, they were $4,000 an acre foot.

Under Nevada law, all water within the boundaries of the state belongs to the public. The owner of a water right does not own the physical water itself. In this light, some of the terms used to describe water rights — “vested,” “perfected” and “certificated” — might convey a false sense of title, permanence or finality. No person can own or acquire title to water. Rather, they merely have the right to beneficial use.

In the first instance, the state engineer allocates such rights to beneficial use through a permitting process. The first step is to file an application with the state engineer, including a $250 fee, and a supporting map prepared by a water rights surveyor showing the point of diversion and place of use of the water.

If the application is approved, a permit is issued granting the right to appropriate, or when it comes to groundwater, pump, a certain amount of water for a particular purpose. The permit will contain mandatory conditions, a timeline for constructing wells and associated works.

When the conditions of a permit are satisfied, and certain filings have been made, including a proof of completion of works (that is, drilling of a well or installation of pump), and a proof of beneficial use (that is, showing that the quantity of water actually being used for the intended purpose), the state engineer will issue a certificate (representing a “certificated” or “perfected” water right).

That does not mean that all certificated (or so-called perfected) water rights are equal. Nevada water law boils down to two maxims: “first in time, first in right,” and “use it or lose it.” The former recognizes the first person to put the water to use has a right to that quantity of water senior to all subsequent users. The latter means that the water must be put to a beneficial use or the right is lost and the water reverts to public ownership. These two maxims generally comprise the prior appropriation doctrine.

Farmers use the great majority of the West’s water, which they get at bargain rates. Even in California, by far the most populous state in the region, four times as much water is poured onto farmland as runs out of taps or is sprinkled over lawns. Farmers in the Imperial irrigation district, east of San Diego, pay $17 per acre-foot of water. In San Diego a household that used the same amount in a year would pay $1,311.

It makes sense to grow some crops in California. No place in America so closely resembles an open-air greenhouse as does the 400 mile-long Central Valley, which produces much of the nation’s fruits and nuts. In 2005 California’s almond crop had an export value of $1.8 billion. More ecologically dubious, however, are the state’s vast cotton and alfalfa farms. This year more than half a million acres (200,000 hectares) of what would otherwise be desert were devoted to the cultivation of rice, much of which was exported to Japan.

Because the supply of water in the West can’t really increase, water managers spend their time looking for ways to adjust its allocation in their favor. The cities would, of course, pay much more for the farmers’ water than could possibly be made growing rice. But the water is not always the farmers’ to sell. Many sources belong to water districts, which require the approval of all members before a transfer can take place. Rural politicians tend to oppose the idea of letting fields turn to dust in order to fill the swimming pools of Las Vegas and Beverly Hills. And, while California has an extensive infrastructure for moving water around between users, many states, including Nevada, do not.

Yet the cities’ desperation, and their consequent willingness to pay top dollar for water, is speeding the development of a water market. Clay Landry of WestWater, a consulting firm, points out that cities can get hold of the stuff much more quickly by buying it from farmers than by building reservoirs and desalination plants. Water contracts are becoming more sophisticated: southern California’s cities routinely buy options to guarantee supply in dry years.

Thus, the opportunity lies with those who have the capital and expertise to buy water rights currently used for agriculture and deliver them to municipalities at higher prices. There is a publicly traded company called PICO Holdings (Nasdaq:PICO) that has successfully made this its business. If the drought in the Southwest persists or worsens, PICO will be in a position to profit from it. In my next post, I will discuss why I think PICO’s shares make a good investment.

Buying Altius Minerals (TSX:ALS)

Altius Minerals (TSX: ALS, Pink Sheets: ATUSF) is my favorite stock and the largest holding in my portfolio. I initially purchased the stock in 2004 at about C$3.75, but I have recently added to my position at prices as high as C$23.60.

Altius started up exactly ten years ago as a small grass roots mineral exploration company. Management’s mission was to leverage its intellectual capital by identifying promising early stage projects in the province of Newfoundland and Labrador and joint venturing them to partners who could earn partial ownership interests by funding their development. The joint venture model allowed the company to reduce cash burn and equity dilution while gaining exposure to a number of promising projects.

History of Success

In 2003, Altius paid $13.6 million to acquire a 0.3% net smelter royalty on the Voisey’s Bay nickel deposit in Labrador. The company hoped that the revenue stream from the royalty would fund entire future exploration expenses. Since then the nickel price has doubled and resource estimates have increased at Voisey’s Bay. Using a conservative $7/lb nickel price and $1.50/lb for copper, Altius’ royalty is worth $58 million.

In 2005, Altius packaged its Rambler copper-gold project and sold it to a newly formed company called Rambler Mines (TSX: RAB) in return for a 30% equity interest in Rambler. At today’s prices, the equity interest is worth $16 million. Altius total investment in the Rambler project amounted to only $500,000.

Similarly, in 2006, Altius spun of its uranium projects into a new company called Aurora Energy (TSX: AXU). Since then Altius has sold $65 million of Aurora stock and still retains a stock position worth $90 million. That is, Altius gained $155 million from an investment of less than $1 million in its uranium properties.

Not surprising, Altius shareholders have been rewarded with a 5-year compound annual growth rate in the share price of 80%. This year alone the stock is up 155%. One would think that it would be impossible for management to deliver these kinds of returns to investors again, but with its recent entrance in the oil refining business they may be able to pull it off.

Newfoundland and Labrador Refining Corporation

On February 9, 2006, Altius announced that it had acquired a founding stake in a new private company called Newfoundland and Labrador Refining Corporation (NLRC) that would evaluate the economic viability of an oil refinery at Placentia Bay in Newfoundland and Labrador. Altius acquired an initial 37.5% stake with the remaining equity divided among three European investors: Dermot Desmond, founder of Dublin-based International Investment and Underwriting; Scottish financier Harry Dobson; and Stephen Posford, former head of European operations for investment bank Salomon Brothers.

NLRC’s feasibility study concluded that a 300,000 barrel per day (bpd) oil refinery costing $4.6 billion, which would rank among the largest and most advanced crude oil processing plants in the world, would be economically viable. The refinery could be completed and begin processing oil by 2011, with the option to expand capacity to 600,000 bpd.

The refinery is to be built on Placentia Bay in southeastern Newfoundland, on Canada’s Atlantic coast, a location picked to take advantage of high demand for petroleum products in the U.S. Northeast. Placentia Bay is located on the main transatlantic shipping route between North America and Western Europe and is one the deepest ice-free ports in North America, able to accommodate Very Large Crude Carrier (VLCC)-size vessels year-round. The region is currently home to a large industrial workforce and features established infrastructure that has supported other large oil industry related development projects.

There is an existing 115,000 barrel per day refinery at Placentia Bay owned by Harvest Energy (NYSE: HTE). It is expected that NLRC’s refinery will be of a different configuration than Harvest’s and will therefore not be a competitor.

NLRC believes the best market opportunity for a new refinery in the Atlantic Basin is one that focuses on efficient processing of medium to heavy sour crude oil feedstocks. Such crude oil types are typically priced at a discount since they represent the bulk of global oil reserves and an increasing share of global crude oil production. The optimal suggested product mix is one that maximizes production of transportation fuels, especially ultra low-sulphur diesel and jet fuel, as there are projected shortages for these products in markets in both Europe and North America.

NLRC has received a positive decision from the provincial environmental process, thereby clearing a major permitting hurdle. The company has also signed an engineering procurement and construction management contract with SNC-Lavalin and finalized an agreement with Japan’s IJK consortium for the fabrication of heavy-walled steel reactor vessels. The remaining challenges are securing commercial agreements on feedstock supply and product off take as well as obtaining debt and equity financing.

Recently Altius completed a bought deal financing at $28 per share for gross proceeds of $50,400,000. The proceeds are to be used to increase Altius’ stake in NLRC to up to 51%. To see why Altius’ equity stake in NLRC could turn out to be a huge money maker it is necessary to analyze the economics of oil refining.

Shortage of Refining Capacity

A refinery makes money by purchasing oil and converting it to usable products such as gasoline, diesel, and jet fuel. The difference between the price received for refined products and the purchase price of oil is called the crack spread and determines how profitable a refiner is.

Numerous refineries were constructed during the 1970s to take advantage of high energy prices; but the resulting collapse in demand for refined products led to a glut of capacity and declining refining margins throughout the 80s and 90s. Unsatisfactory return on investment, obsolescence, tight environmental restrictions, and not-in-my-back-yard community opposition forced the closure of half of the refineries operating in 1980 and kept a new refinery from being built since then. Instead refiners made upgrades at existing profitable sites to expand capacity and keep up with demand.

Squeezing Each Barrel

However, to meet continued growth in demand experts estimate the U.S. would have to boost refining capacity by another 250,000 bpd — every year. But it is not clear just how much further U.S. refiners can stretch production. On a worldwide basis crude demand has been rising steadily during this time and has now caught up with capacity creating the need for brand new refineries:

Refining Spare Capacity

New Complex Refineries Are Needed

When crude oil is refined, it produces several products, including gasoline, diesel and jet fuel. Depending on how a refinery is configured, it will produce varying amounts of these products from a single barrel of crude. In decades past, European refiners invested heavily in refining equipment that emphasized gasoline production. But a renewed groundswell in Europe in the past decade to reduce carbon dioxide and other greenhouse-gas emissions, as well as improvements in diesel technology, have accelerated the Continent’s drive towards diesel fuel.

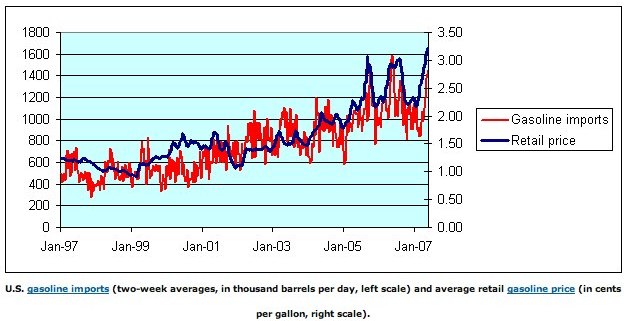
As a result, Europe has a shortage of diesel and a glut of gasoline, which is exported to the U.S. As shown below, the U.S. has become increasingly dependent on gasoline imports:

US Gasoline Imports

The crude oil that is purchased as feedstock for refining operations could be the light sweet crude oil that trades on the NYMEX, which is light due to high API gravity and sweet due to low sulfur content. On the other hand, refineries could purchase a cheaper crude grade that is heavy, or sour, or both, but which would require unique refining parameters.

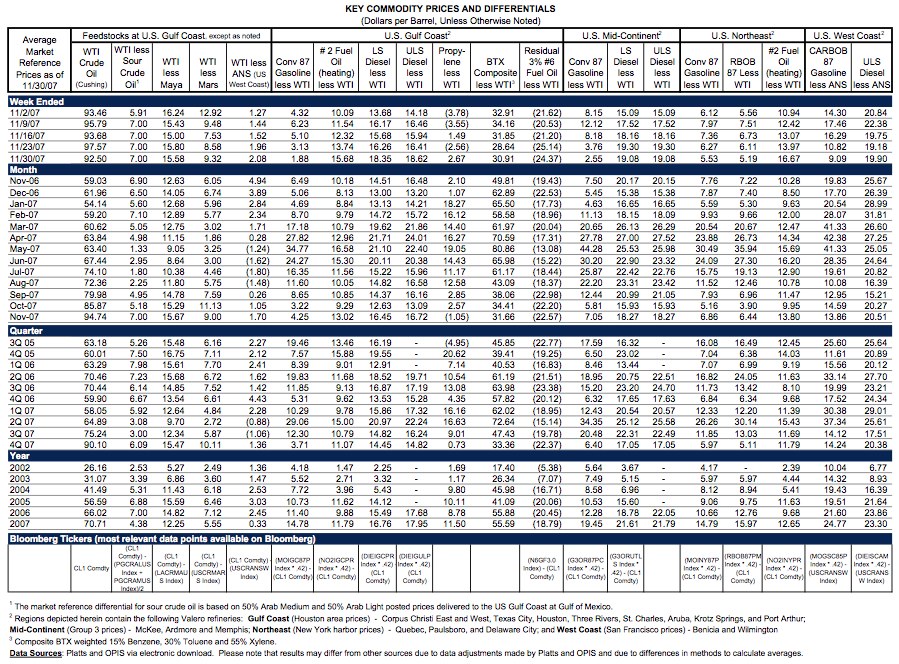
The lack of U.S. spare refining capacity coupled with the inability of existing refineries to utilize heavy sour crude and produce the optimal mix of products to match demand has led to rising crack spreads. As the following tables show, the spread between West Texas Intermediate (WTI) light sweet oil and Mexican Maya heavy sour oil has been widening since 2002. If NLRC was in operation now and it utilized 100% Maya crude as feedstock, rather than WTI, it would enjoy a gross margin of approximately $26.

Valero Spreads

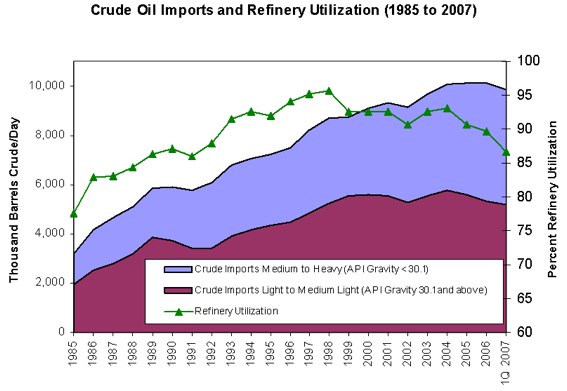
Maya is selling at a substantial discount to light sweet because a growing proportion of oil production is of the heavy sour type. Furthermore, North American refineries, almost all of which were built over 25 years ago when light sweet was plentiful, are not configured to process oil that is heavy and sour. Thus, stagnant demand and growing supplies has made Maya a relatively cheap feedstock for refineries that are complex enough to process it.

Quality of Crude Oil Imports

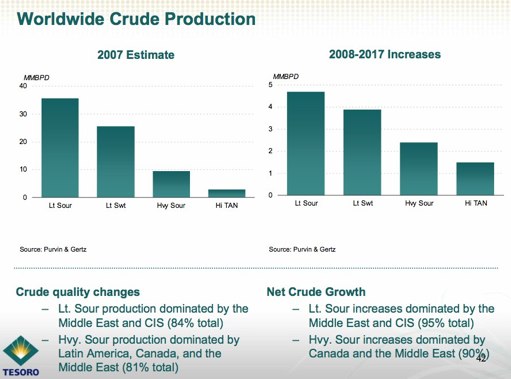
The following graphic indicates that the WTI-Maya spread is likely to continue increasing over the next 10 years:

Future Crude Oil Production By Grade

I do not subscribe to the theory of Peak Oil, though as I implied in this post, I do believe that we have peaked in the production of light sweet crude. The world has plenty of oil left in places like the Athabasca tar sands and the Colorado oil shales, however a growing proportion of the oil to be produced will be of the heavy sour type.

Whereas supply has become increasingly poorer in quality, the demand for products has risen rapidly. Also, the quality requirements for light products have become ever more strict. Sulfur levels in transportation fuels have tightened significantly in recent years. Nearly 40 per cent of the world’s crude distillation capacity is more than 25 years old and cannot be overhauled to meet the new requirements. With global warming becoming an ever popular issue, this trend will remain intact for the foreseeable future.

Thus, we are now in an environment where building a new complex refinery makes sense. However, as mentioned tightening environmental standards coupled with the fact that most people do not want a refinery in their backyards means there are no current plans for a greenfield refinery in the U.S. Since it takes 4 to 5 years to construct a refinery from scratch, the growth in demand for refined products over this time period will have to be met by expanding capacity at existing U.S. refineries and through imports.

However, current refineries are less efficient at converting heavy sour feedstock as evidenced by the frequent outages experienced by refineries recently. Therefore, NLRC, which will have one of the most complex refineries in the world, will enjoy a significant competitive advantage and will be able to capture the highest margins.

New International Refinery Projects

Companies in India, China and the Middle East are rapidly building refineries to meet surging demand, adding capacity that could bring down prices. Global refining capacity is expected to grow 1.7% a year for the next five years, a significant rate of increase for a traditionally slow-moving industry, according to Cambridge Energy Research Associates. NLRC’s target markets for its refined products will be the U.S. Northeast (for gasoline and jet fuel) and western Europe (for diesel). Given Placentia Bay’s proximity to these locations, NLRC will be able to deliver its refined products more cheaply than Asian refineries.

Recently, Irving Oil submitted an environmental plan for constructing a new 300,000 bpd refinery in nearby New Brunswick with the plan to start up around 2012. There is some opposition from the communities near the proposed site and environmental permits will still need to be granted from the province. But even if the project gets the green light to proceed, it should not pose a threat to NLRC. Considering that the US is under supplied by 4 million bpd of refined product, two 300,000 bpd refineries on the Atlantic coast can certainly coexist and thrive.

Eventually, rising crack spreads will lead to several new refinery projects in the U.S. But since none have been currently announced, NLRC should enjoy a number of lucrative years before capacity does eventually catch up to demand. As Altius’ Vice President of corporate development, Chad Wells stated, “We recognize to a certain degree there is a race in place in the sense of filling this capacity — this insatiable northeastern U.S. market as well as diesel demand in Europe.”

Valuing Altius

The cost of constructing the refinery has been estimated at $4.6 billion, but I would not be surprised to see it cost much more than that. To be very conservative, I will assume a price tag of $6 billion. NLRC has yet to secure debt financing, but I expect its capital structure would be comprised of something like two-thirds debt and one-third equity.

Therefore, stock holders will have to foot $2 billion of the bill, of which $1 billion will need to be contributed by Altius if it wanted to own 51% of NLRC equity. Obviously, Altius cannot afford that and will have to suffer dilution during further equity rounds. However, I think it is likely that Altius can hold onto at least 15% of NLRC’s equity. Under this scenario, Altius would have to contribute approximately $150 million, which is easily manageable considering the company is sitting on $165 million in cash.

If NLRC were operating today, it would enjoy gross margins of $26/barrel and an operating margin of $20/barrel. If we assume that the refinery manages to utilize 90% of its 300,000 barrel/day capacity, then the company would earn nearly $2 billion per year. Most refiners are currently trading for 5 times operating income which means NLRC would be valued at $10 billion. Thus Altius’ 15% stake would be worth $1.5 billion.

In addition, Altius owns a 62% stake in a 1% to 10% sliding scale royalty based on gross refining margins between $4 and $20. Assuming Altius is able to keep this royalty through to production, and I see no reason why they will not be able to, Altius’ royalty would amount to $120 million per year. If a valuation multiple of 10 was to be applied to the annual royalty, it would be worth $1.2 billion. Thus, Altius’ NLRC stake would be worth $2.7 billion or $90 per Altius share. If Altius’ other assets were included the stock could be worth $100 by the time NLRC begins operation.

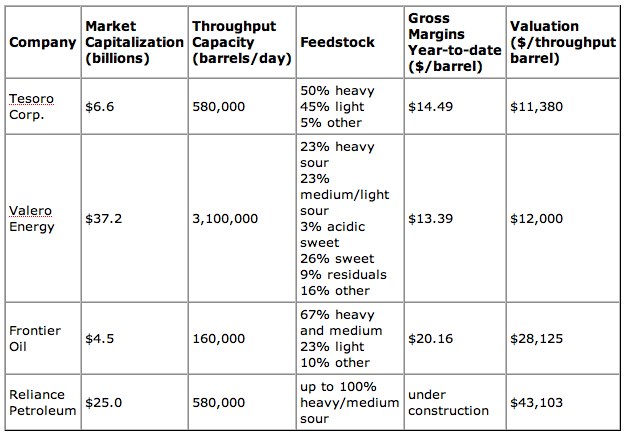
In a recent research report by Haywood Securities, NLRC’s valuation was extrapolated by comparing it to another pure play refiner, Reliance Petroleum, which has only one asset: a 580,000 bpd Indian refinery scheduled to begin operating by this time next year. It will have a complexity of 14.0, using the Nelson Complexity Index, ranking it amongst the highest in the sector and similar to NLRC’s proposed refinery. Reliance Petroleum currently trades on the Bombay Stock Exchange and is priced at over $40,000 per barrel of capacity. Applying this valuation to NLRC yields a value of $12 billion. Altius’ share of this $12 billion plus the royalty would make its stock worth $110.

As the following table shows, there is a premium attached to the valuations of complex refiners:

Comparison of Refiners

Markets do work and and eventually huge refining profits will attract several new refinery projects. However, permitting and construction takes at least 5 years and NLRC is well ahead of anyone. If for some reason the refinery project fails to be completed, Altius’ share price will collapse to its net asset value of $10. But given the track record of the management team and the project is backed by several prominent investors and the government of Newfoundland and Labrador, I am betting that the refinery will get built. In conclusion, I believe Altius is a cheap, though speculative, way to play the complex refining theme.

Covered My Shorts

This past week I covered my short positions in Yahoo (NASDAQ:YHOO) at $27.65, Dick’s Sporting Goods (NYSE:DKS) at $28.29, and HOLDRs Retail ETF (AMEX:RTH) at $93.26. I am no longer shorting any stocks. I covered these positions not because I don’t believe they could fall further, but due to my eagerness to increase my already massive exposure to gold and to start new positions in Canadian junior natural gas stocks, Quest Capital (TSX:QC, AMEX:QCC), and PICO Holdings (NASDAQ:PICO). Since my cash was fully invested I needed to free up some margin, hence the short covering.

It may seem that my buying of gold investments amounting to more than 100% of the equity in my portfolio is risking financial death (which I concede), but especially so after gold has moved up from $650 to $832, a 26% gain in less than 3 months. But as a Canadian resident I am more concerned about the Canadian dollar gold price than the US dollar gold price. In Canadian dollar terms, the gold price has increased by only 10% since mid-August. The Canadian dollar has been extraordinarily strong recently, but in my opinion is wildly over-priced against gold given that the Bank of Canada has been as proficient with the money printing presses as the Federal Reserve.

But despite the 10% rise in the Canadian dollar gold price since August, the TSX Venture Exchange listed junior explorers haven’t seen much of a rise in their share prices, although an environment of higher gold prices increases the likelihood of making a discovery. While the majors have rallied along with the gold price, the juniors have underperformed and I don’t expect this to continue. I bought some more shares of my favorite juniors and plan to continue accumulating them if they become cheaper.

I also decided to buy shares of some mining companies who would immediately and directly benefit from a rising gold price. Miners have struggled to contain costs due to lower grades being extracted, higher energy prices, rising wages, and strengthening foreign currencies. Thus, despite an increasing gold price, margins have not been expanding. But recent developments in the US credit markets lead me to believe that we will see accelerating worldwide monetary inflation which will cause gold to outperform just about anything else in the next couple of years.

I purchased shares of Agnico-Eagle Mines (TSX:AEM, NYSE:AEM) at C$50.78, Royal Gold (TSX:RGL, NASDAQ:RGLD) at C$27.89, Vista Gold (TSX:VGZ, AMEX:VGZ) at C$5.82, and Silver Standard (TSX:SSO, NASDAQ:SSRI) at C$41.80. Mining is a lousy business and these stocks aren’t cheap, but I suspect that they will be the first to benefit from a rising gold price, followed by the juniors. My investment in theses stocks represents a tiny portion of my overall portfolio, so I am hoping they correct in the short-term so that I can add to my positions at lower prices.

As a believer that we are in a secular bull market in commodities that still has another few years to run, I am constantly on the prowl for investment opportunities in the sector. At the same time, my contrarian style has discouraged me from making any investments at a time when commodity funds have recently been some of the best performers. However, I think I may have found a couple of commodities that are still cheap.

Natural gas is cheap based on historical inflation-adjusted terms and when compared to the price of oil. Also, there are strong fundamental reasons to believe that natural gas prices will double within the next few years. I will discuss these reasons in a future post. Canadian junior natural gas stocks have been pummeled in the last couple of years due to falling gas prices and a Canadian government ruling which eliminates the favorable tax treatment enjoyed by income trusts who were aggressive acquirers of junior gas companies in recent years. But the market is overlooking the fact that as Alberta oil sands production ramps up, the natural gas assets owned by the juniors will become attractive once again.

I am currently accumulating Canadian natural gas stocks, but since they are microcap penny stocks I am reluctant to mention them in this blog. One company I will reveal, due to its $1.2 billion market cap, is AltaGas Income Trust (TSX:ALA.UN) which I purchased at C$ 25.53 two weeks ago. Altagas doesn’t actually have any natural gas properties, but rather owns an expansive network of gas gathering lines and transmission pipelines in Alberta. If the desperate scramble for natural gas assets plays out as I envision, then Altagas’ infrastructure will become much more valuable.

Another commodity which I think is still cheap is water. Currently, there aren’t many avenues for water investing (which reminds me of uranium several years ago, before the uranium price skyrocked and uranium companies sprouted like weeds in a neglected lawn). There are several publicly-traded water technology and treatment companies, but the most direct way to benefit from water scarcity is to own water rights. PICO Holdings (NASDAQ:PICO) is the largest private owner of water rights in Nevada, which is probably the best place in the world to own water rights. Due to global warming, the occurrence of a catastrophic drought is a question of when, not if, and at that time the value of water will go through the roof.

In addition, I purchased Quest Capital, an asset-backed lender, at C$2.61 which I had previously owned, but sold because I was afraid of the possibility of turmoil in the credit markets which might unfairly punish the company’s shares. It turned out to be the right move and I feel more comfortable buying back the stock now that the credit crunch has become front page news. Last week, I also added to my position in Altius Minerals (TSX:ALS) at $23.61. I already own a boatload of Altius stock and it is by far my largest holding. I am confident Altius will complete its mission of building the first new refinery in North America in decades. I will post a more detailed write up on both Quest and Altius in the future.

Shifting My Short Positions

I have been traveling lately and haven’t had time to write any posts, but I do want to make a quick note: last week I had closed my short position in MBIA (NYSE:MBI) at $46.47 and Target (NYSE:TGT) at $58.00.

The reason for shorting MBIA is expressed here, and the underlying problems with their business have come to surface. The stock has actually fallen further and currently trades for $35.29. Fitch Ratings has stated that it will be reviewing the capital of MBIA and other bond insurers to ensure that their AAA ratings are appropriate. A downgrade would be disastrous and I would not be surprised to see one of the major insurers eventually default. However, I no longer see MBIA as a “no-brainer” short that it was in September when I shorted the stock at $61.29 so I am taking the 25% profit.

I also covered my Target short after initiating the position in July at $66.77. A 13% gain in four months is good enough for me, though I think the stock could continue to decline. The main reason for covering was that I found a more attractive shorting opportunity…

Last week, I decided to short Yahoo (Nasdaq:YHOO) at $32.26. The company is losing market share — in terms of searches and time spent on Yahoo properties — to Google (Nasdaq:GOOG) and social networking sites, in particular Facebook and MySpace. As a result, the company is having a tough time growing earnings yet trades at 70 times this year’s estimated earnings. I expect the market will eventually realize this and the stock to decline below $25 at some point.

In looking at my posts, it occurred to me that I forgot to mention that I covered my Black & Decker short at $79.14 on October 18. This resulted in a 16% gain in four months. Besides Yahoo, my remaining shorts are Dick’s Sporting Goods (NYSE:DKS) and Retail HOLDRS ETF (AMEX:RTH).

Adding to My Gold Position

Gold hit a 27-year high last week in response to the Fed’s 50 basis points cut which showed that the central bank was more concerned about economic growth than restoring confidence in the US dollar. The economy is on the path to a recession and it looks like the Fed and the government will do everything in their powers to prevent it, and in the process, devalue the dollar against other currencies and gold.

Earlier in the year, I was a net seller of gold stocks (as discussed here and here) due to my fear that a liquidity crisis would soon develop and all assets, including gold, would endure some short-term weakness. The liquidity crisis did occur, and though gold held up well, junior gold explorers have declined by 30% to 50% since August. While I am still pessimistic on a significant rebound for bonds and equities, gold should see gains thanks to the Fed’s expansionary monetary policies.

I have now started to increase my position in gold juniors and will continue to do so in the coming weeks until I am fully invested in the sector again. The gold price may pullback, but the gold juniors have been beaten up so badly that a lot of the risk is gone. I am more confident than ever that we will see $1000 gold within the next couple of years and I want to position my portfolio again to benefit from that.

Shorting MBIA

Today I shorted MBIA (NYSE:MBI) at $61.29. The bearish outlook for MBIA is presented here. Basically, MBIA is a credit insurer of products such as municipal bonds, MBS, and CDOs. The problem is that the company has insured over $200 billion of structured finance assets while maintaining a total statutory capital base of only $7 billion to payout on defaults. Therefore, a mere 3% structured finance loss will wipe out MBIA’s entire capital base.

And even if structured finance losses remain under 3%, a loss of as little as $500 million in MBIA’s statutory capital base could impair its AAA rating. That would put it at a significant competitive disadvantage against other credit insurers.

I want to point out that I ordinarily would not short a stock like MBIA. But most of my portfolio consists of microcap gold juniors whose share prices are very vulnerable to a further deterioration in credit markets and a deflationary environment. If this occurs, then shorting a stock such as MBIA should hedge against some of my losses.MBIA