I am of the opinion that the US economy has just slipped into the worst consumer spending slump in decades. This will lead to a sharp pullback in big ticket purchases. Automobile sales, which tend to be financed, are especially vulnerable given the current problems in the credit markets. Moreover, the average US household owns almost two vehicles meaning that the market is saturated. Most new demand will come from replacement and this need, too, is declining as cars released in recent years are lasting longer. Another consideration is the rise in energy prices which is leading to a shift in demand from SUVs and light trucks to more fuel efficient cars.
The US auto companies are already in trouble due to their significantly greater cost of labor compared to their Asian competitors. European manufacturers also face this challenge, but their efficiency and technological superiority have allowed them to carve out a niche in the luxury market where they can more easily pass on their costs to their customers. GM, Ford, and Chrysler have been losing market share for years and are burning cash at an alarming rate. Bankruptcy is only a question of time.
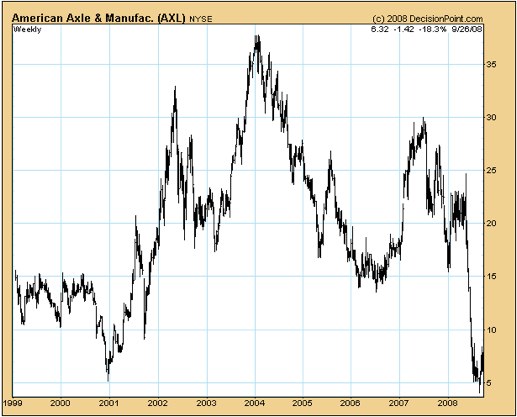
Shorting GM and Ford should be profitable but even better shorting opportunities can be found among small auto parts manufacturers who are dependent on supplying the Big 3 and are focused on making parts for gas guzzling vehicles. American Axle & Manufacturing (NYSE: AXL) fits this bill and I initiated a short position last week at $7.58. AXL manufactures driveline and drivetrain systems for light trucks and SUVs. In 2007, 78% of its sales were to GM and another 12% to Chrysler. AXL’s stock price has already collapsed, but I believe the company will file for bankruptcy in the not too distant future and the stock will go to zero.
The following is AXL’s key financial data:
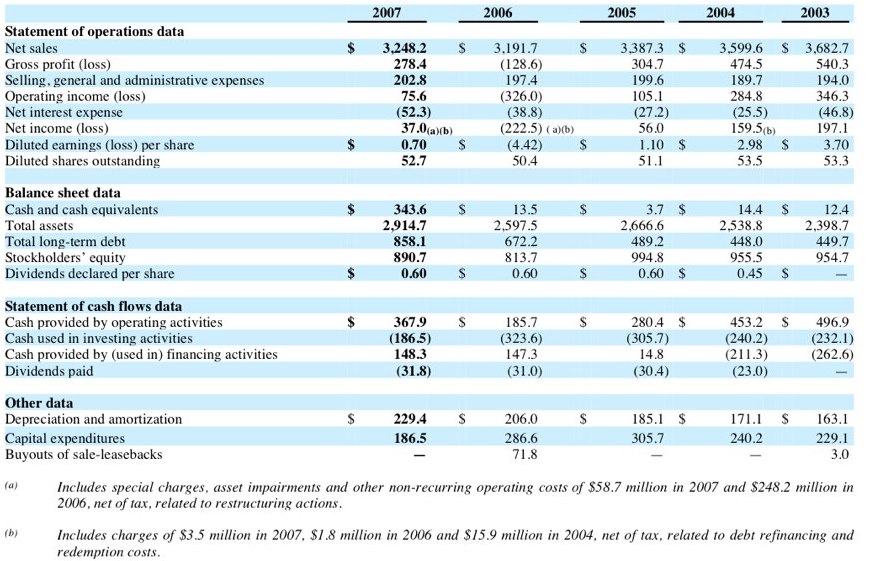
Sales have been trending lower for the last 5 years and have started to plummet in 2008.
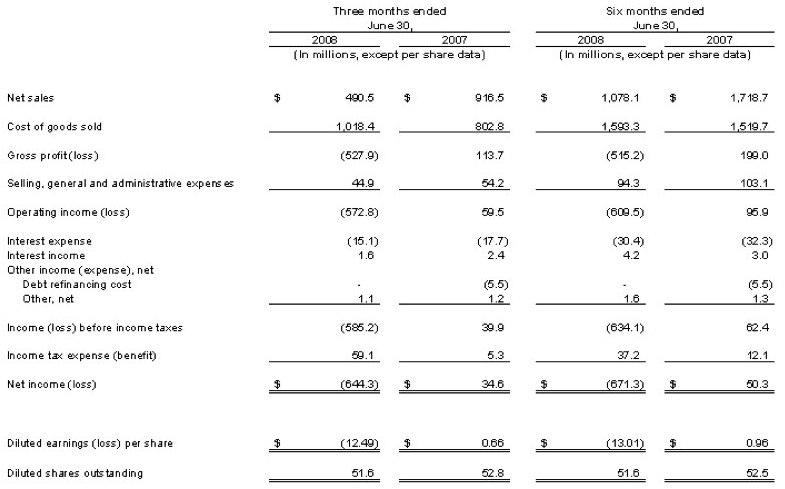
AXL’s results in the first half of 2008 were severely impacted by a strike called by the International UAW. AXL estimates the reduction in sales and operating income resulting from the International UAW strike to be $414.0 million and $129.4 million ($2.57 per share), respectively. Even if this is a correct estimate and we exclude the impact from the strike, then sales would have been 13% lower year-over-year and there would still be a loss.
Since AXL is currently losing money the important question is how much cash is the company burning. Here is the 2nd quarter cash flow statement.
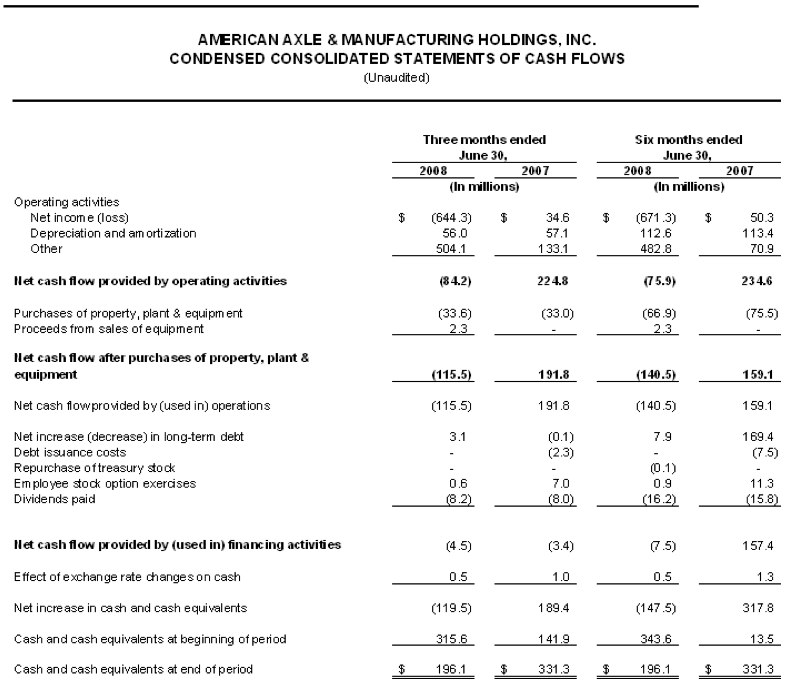 AXL had free cash flow (defined as cash flow provided by operating activities less capital expenditures) of negative $25 million and $115 million during the first and second quarters, respectively. This burn rate needs to improve as the company has only $196 million in cash.
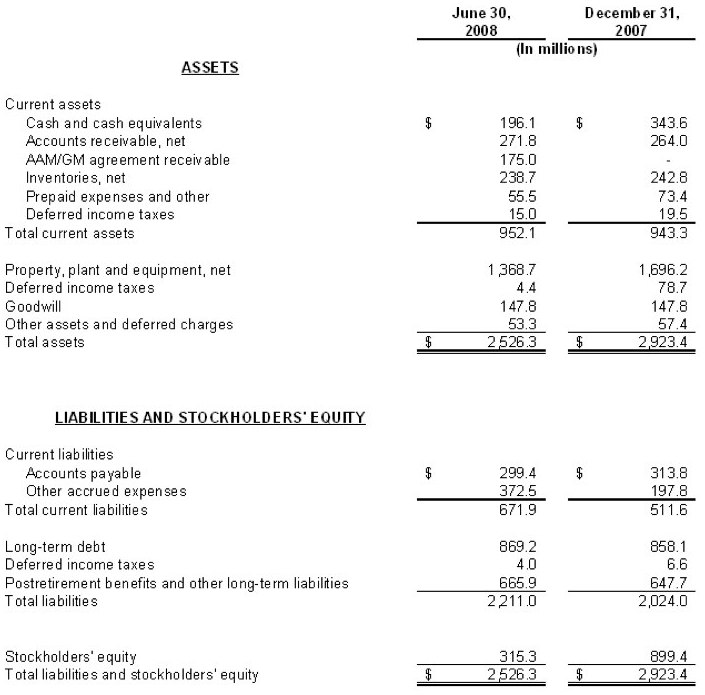
AXL does have $600 million available under a revolving credit facility. However, this facility contains financial covenants which requires AXL to comply with a leverage ratio and to maintain a minimum level of net worth. A violation of either of these covenants could result in a default under this facility, which would permit the lenders to accelerate the repayment of any borrowings outstanding at that time. If AXL does not draw funds from this facility soon, there is a good chance it will eventually get pulled by banks who are trying to shrink their balance sheets.
Another problem is the rising unfunded pension and postretirement benefits valued at $524.4 million at the end of 2007.
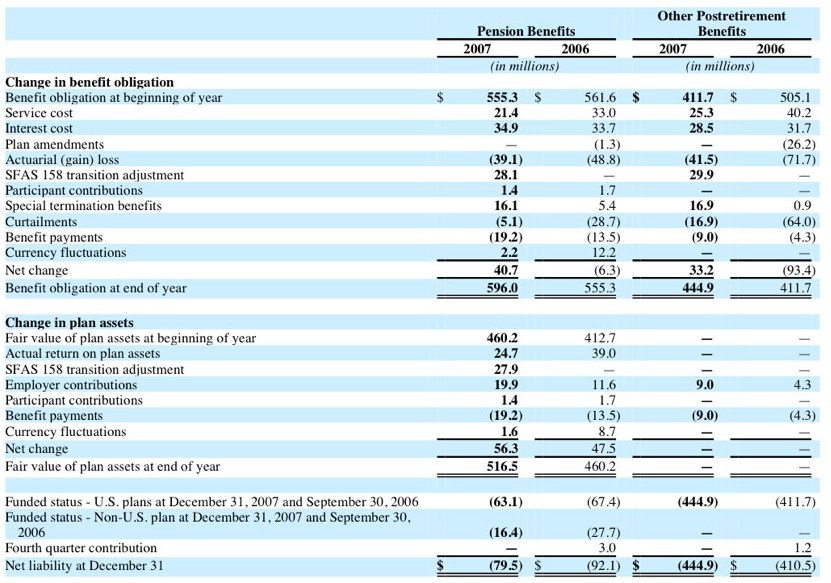
This net liability is estimated using an expected return on plan assets of 8.50% and a discount rate of 6.45%. In my opinion, these are optimistic assumptions since I believe that equity prices are in a secular bear market and interest rates will rise. If so, then AXL’s cash outlays could be significantly greater.
AXL is currently trading for 30% less than the price I shorted at just last week. Although I believe the stock is heading to zero, if I had no short position I would short a little bit now and wait for a rally to increase the position. It’s my expectation that AXL along with many other US auto companies are going to struggle to survive.
